

NetBenefits - Fidelity at Work
by Fidelity Investments
4.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.0
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
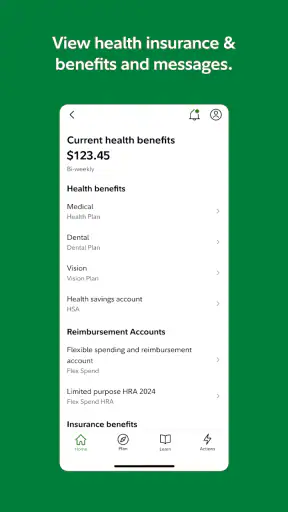
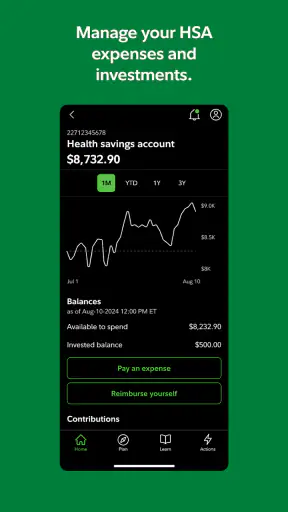
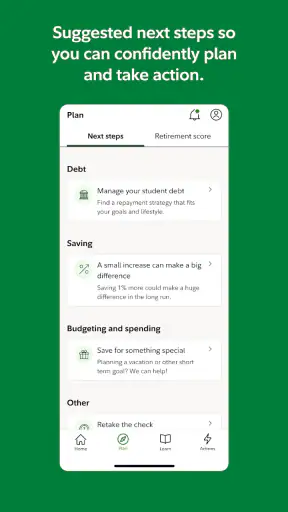
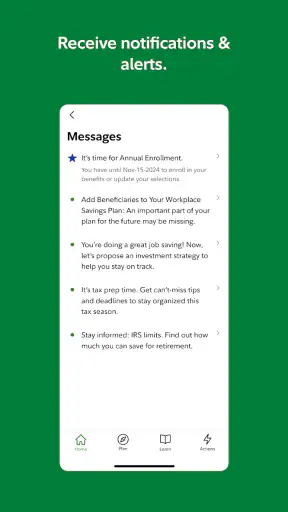
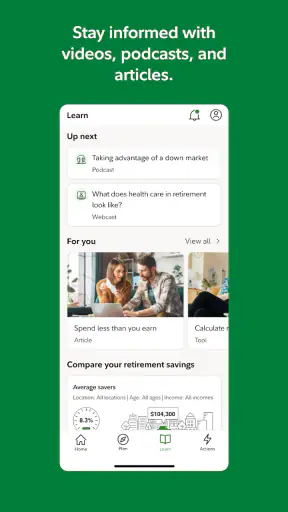
 Analysis by Getfullapps
Managing a workplace retirement account is usually something I would rather do in a few focused minutes than turn into a long financial task. That is where NetBenefits - Fidelity at Work makes sense. It is a free finance app from Fidelity Investments for people who need to check and manage their Fidelity workplace accounts from a phone. I found its strongest quality to be its direct purpose: it is not trying to be a general banking app, a stock-trading playground, or a complete personal-budgeting tool.
That narrow focus is useful, but it also sets expectations. The app is best understood as a mobile doorway into employer-sponsored Fidelity accounts. If your workplace plan is held there, it can be a practical way to review information while away from a computer. If you want a broad view of accounts from several providers, you may find a dedicated budgeting or financial-aggregation service more suitable.
How NetBenefits handles readability and navigation
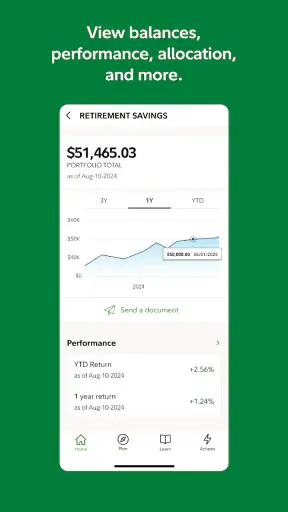
My first impression is that the app is organized around the questions most workplace-plan users actually ask: what is in the account, how is it performing, and what actions are available? That is a more helpful starting point than forcing every person through a general investment dashboard. The experience feels task-oriented, which matters when I am checking a retirement contribution during a short break rather than sitting down for a full planning session.
The app comes from Fidelity Investments and has been available since 2013, so it is not a brand-new experiment. Its current version is 4.35.2, and the product has reached over a million installs with an average rating of 4.0 from around twenty-five thousand ratings. Those figures suggest a well-established workplace-account tool, although popularity alone does not guarantee that every employer plan will feel identical inside it.
Readability is especially important in a finance app because a small misunderstanding can affect a serious decision. I would use the app for quick confirmation first: checking whether a contribution appears, reviewing an account balance, or looking at the general direction of a plan. For detailed comparisons between investment choices, retirement projections, or complicated distribution decisions, I would slow down and verify the information rather than relying on a quick glance at a phone screen.
A useful habit is to separate viewing from acting. I can open the app to understand my current position, then pause before changing a contribution rate or making another consequential decision. This is not a criticism unique to NetBenefits; mobile interfaces naturally encourage fast taps. The practical lesson is that a clean screen should make information easier to find, not make a major financial decision feel casual.
The app’s short name, NetBenefits, can also create a small recognition issue for new users. Someone may search for a Fidelity-branded workplace tool and wonder whether they have found the correct application. The connection becomes clearer once the app is understood as the workplace-account side of Fidelity rather than the company’s general investing experience. I would advise new users to confirm the developer shown in the app store and use their normal account credentials carefully, especially when several Fidelity apps appear in search results.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Useful navigation habits for different reading needs
For users who read slowly, need more time to process financial terminology, or are easily overwhelmed by dense account information, I recommend opening the app with one question in mind. “Did my latest contribution arrive?” is easier to answer than “I should review everything.” Narrowing the task reduces visual and mental load and makes it less likely that an important figure will be mistaken for another.
I also prefer reviewing one account area at a time rather than jumping between balances, investments, and workplace-plan details. A short pause after each screen helps distinguish current value, contribution information, and performance information. That distinction is important because these figures answer different questions. A balance is not the same thing as a contribution, and recent performance is not a promise about future results.
There is a trade-off here. A mobile app can make routine checking more approachable, but it cannot replace the larger view and slower pace of a desktop browser for every reader. People who need large text, a wider layout, or more room to compare several pieces of information may find Fidelity’s web experience easier for complex reviews. I would use the phone app for monitoring and the larger screen for careful planning when possible.
Motor, sensory, and cognitive considerations
Financial apps need to work for more than a person with perfect vision, steady hands, and unlimited attention. In everyday use, NetBenefits is most comfortable when I have a stable connection, enough time to read, and the ability to interact accurately with a phone. That means the experience can vary significantly between a calm home setting and a crowded commute.
For someone with limited dexterity, the main concern is the risk of making an unintended selection while moving through account actions. I would avoid rushing through screens and would reserve changes to contributions or account settings for a quiet moment. If a user has difficulty with precise taps, the safer workflow is to use the app primarily for review and complete more involved actions on a larger device when that is available.
Users with low vision may benefit from the ability to adjust their phone’s system display settings, but the result depends on how the app responds to those settings and on the individual’s needs. I would test text enlargement, display scaling, and the phone’s built-in spoken or magnification tools before depending on the app for an urgent account task. A screen that looks readable at the default setting may become harder to interpret when system text is enlarged or when several financial labels sit close together.
People who are sensitive to visual clutter may appreciate the app’s focused purpose compared with a general finance dashboard filled with unrelated accounts and alerts. At the same time, workplace-plan terminology can still be mentally demanding. Terms connected with contributions, investments, distributions, and account activity are not interchangeable. I would encourage a first-time user to explore during a low-pressure moment and write down any unfamiliar term before making a change.
For users who rely on spoken feedback, the most responsible approach is to try the relevant phone accessibility tools directly with the current app version. Spoken output can be helpful for reading labels and values, but financial information is only useful when the reading order and context are clear. If a screen reader announces a number without making its label obvious, I would verify the same information through another view or through Fidelity’s broader support channels before acting on it.
This is an area where I would avoid making sweeping claims. A finance app may be usable with a particular person’s settings and still be frustrating for another person with different needs. NetBenefits provides value when its information can be read and understood comfortably, but users who depend on highly specialized assistive workflows should test their specific setup before treating it as their only access point.
When the phone is not the ideal device
A phone is convenient because it is usually nearby, but convenience can work against careful reading. A small display, bright sunlight, glare, background noise, or one-handed use can turn a simple review into a concentration test. I would not make a retirement-account change while walking, standing on public transport, or trying to remember several instructions at once.
A better everyday routine is to check the account when seated, increase the phone’s display size if needed, and keep the session focused. If a family member or support person helps with financial tasks, the account holder should remain in control of credentials and decisions. The app can make access easier, but it does not remove the need for privacy and deliberate confirmation.
For people who have difficulty with touch input, voice interaction through the phone may help with navigation, but voice commands are not a substitute for carefully reviewing sensitive financial details. I would use voice tools to open or move through the app only when the resulting screen can still be checked visually or through a trusted assistive method. The final confirmation should never be treated as automatic simply because the navigation was hands-free.
Access in real-life situations
The most convincing use case for me is a short workplace moment. Imagine receiving a pay statement and wanting to confirm that a retirement contribution reached the account. Instead of waiting until returning home to open a browser, I can use the phone to check the relevant account information. That can reduce uncertainty, particularly when a person is trying to build a regular habit of monitoring workplace savings.
Another useful situation is preparing for a conversation with an employer’s benefits team. I can review the account beforehand, note what I understand, and identify the exact question I need to ask. This is more productive than opening the app in the middle of a conversation and trying to interpret unfamiliar information under pressure. The app works best as preparation and confirmation, not as a replacement for human explanation when plan rules are complicated.
Travel is another context where mobile access is valuable. A user may want to check an account while away from a home computer, but I would distinguish between access and action. Viewing information during travel can be convenient; changing an important setting on an airport bench or hotel lobby is less appealing. A secure, private connection and enough time to review the result matter more than the ability to complete a task quickly.
For users with fluctuating energy, attention, or concentration, short sessions are a genuine strength. The app allows the account to be approached in small steps rather than as one large financial chore. A person might check the current account position one day and return later to study an investment or contribution question. That staged workflow is more realistic than expecting every user to understand the entire workplace plan in one sitting.
However, mobile availability does not mean universal convenience. Someone with an older phone, limited data access, unreliable connectivity, or difficulty keeping a device charged may prefer a computer or another support route. The app is free, which removes a direct purchase barrier, but access still depends on having a compatible device and being able to sign in safely.
The listed minimum operating-system requirement is version 12, so people using older devices should check compatibility before planning around the app. This is particularly relevant for users who keep a phone for many years because replacing a device solely for one workplace account may not be worthwhile. In that situation, Fidelity’s browser-based access or employer benefits support may be the more practical alternative.
Who benefits most, and who should choose something else
I would recommend NetBenefits to an employee whose workplace account is with Fidelity and who wants a focused way to stay aware of it. It is a good fit for routine checks, preparing questions, and keeping workplace savings from becoming completely out of sight. It is also appealing to users who prefer a dedicated account experience instead of placing retirement information inside a broad personal-finance dashboard.
I would be more cautious about recommending it as the only financial app for someone who wants household budgeting, bank-account aggregation, bill tracking, or a complete picture of several investment providers. NetBenefits is centered on Fidelity workplace accounts, so a general finance app may be better for that wider job. A brokerage app may also be more appropriate for someone primarily interested in active personal investing rather than employer-sponsored benefits.
There is a second important distinction: account access is not the same as financial advice. The app can help a user see and manage information connected with a workplace plan, but I would not treat a convenient mobile screen as a personal recommendation about how much to save or which investment choice is suitable. Users who need individualized guidance should add an appropriate professional or benefits conversation rather than expecting the app to make that judgment for them.
Families and caregivers should also think about privacy before sharing a device. A person may need assistance reading or navigating the account, but workplace-finance credentials are sensitive. I would prefer a workflow where the account holder decides what to share, enters authentication details privately, and confirms every action. This is especially important when accessibility support involves another person physically handling the phone.
Remaining barriers and my inclusive verdict
NetBenefits succeeds when the goal is straightforward access to a Fidelity workplace account. Its free price, focused purpose, and mobile format make routine monitoring easier than relying exclusively on a desktop computer. The developer’s long presence in this space also gives the app a sense of continuity, while its Everyone age rating makes it broadly suitable from a content perspective.
Still, the app cannot solve every access problem. Small-screen reading, precise touch interaction, unfamiliar retirement vocabulary, device compatibility, and the pressure to act quickly can all create friction. Users with specific accessibility requirements should test the current app with their own phone settings and assistive tools. I would not assume that a generally usable interface will meet every individual need.
My most practical advice is to use NetBenefits in layers. Start with low-risk viewing, learn where the account information appears, and establish a calm routine for checking it. Use a larger screen or another support channel when a decision involves several choices or when the mobile presentation is difficult to interpret. Keep the app for the convenience it genuinely offers without forcing it to become a complete financial-planning system.
After more than a decade on the market and a user base measured in the millions, the app is clearly established rather than experimental. Its 4.0 average from roughly twenty-five thousand ratings is respectable, though it also suggests that the experience will not be perfect for everyone. I see that as a fair summary of the product: useful and focused, but dependent on the user’s plan, device, reading needs, and comfort with financial decisions.
My final view is that NetBenefits is a sensible choice for accessible, on-the-go awareness of a Fidelity workplace account, provided “on the go” does not become “in a hurry.” I would recommend it to employees who want a dedicated mobile connection to their benefits and are comfortable verifying important details before acting. I would steer users seeking broad budgeting, multi-provider investing, or highly specialized accessibility support toward a combination of a larger-screen experience and more suitable tools. Used with that clear understanding, NetBenefits - Fidelity at Work can make workplace savings easier to remember, easier to check, and less dependent on being near a computer.
Pros
- Quick access to retirement balances, contributions, and investment performance.
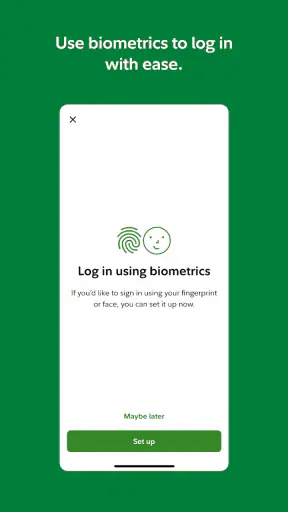
- Supports secure login options such as biometric authentication on compatible devices.
- Useful tools help estimate retirement income and compare contribution strategies.
- Lets users review benefits information and manage eligible workplace accounts remotely.
- Clean interface makes essential account details easy to find on mobile devices.
Cons
- Features may vary depending on the employer’s plan and account eligibility.
- Some transactions or changes may require additional verification or desktop access.
- Investment details can be difficult for beginners to understand without financial knowledge.
- App performance and available services may depend on internet connection quality.
- Does not replace personalized financial advice when making major investment decisions.
FAQs for NetBenefits - Fidelity at Work
What is NetBenefits - Fidelity at Work used for?
NetBenefits - Fidelity at Work is designed to help eligible employees manage workplace benefits through Fidelity. Depending on your employer’s plan, you may be able to review retirement savings, check account balances, monitor investments, access statements, manage contributions, and explore educational resources. The exact features available can vary significantly because each employer controls which Fidelity benefits and services are offered.
Can I use the NetBenefits app if my employer does not use Fidelity?
Generally, NetBenefits is intended for employees whose workplace retirement or benefit plans are administered by Fidelity. If your employer uses another provider, the app may not recognize your information or provide access to your accounts. Before downloading, confirm with your employer’s human resources department or benefits portal that Fidelity administers your plan and that your account is eligible for online or mobile access.
How do I sign in to NetBenefits - Fidelity at Work?
You normally sign in using your Fidelity username and password, or by following the registration process if you have not created online credentials yet. Some users may be asked to complete identity verification or use additional security measures. If you forget your login details, use Fidelity’s official recovery options rather than sharing account information with anyone claiming to provide technical support.
What can I do inside the NetBenefits mobile application?
Available tools depend on your employer’s plan, but the app commonly allows users to view balances, examine investment performance, review contribution activity, access transaction history, and read account documents. Some plans may also support changing contribution rates, managing beneficiaries, or completing benefit-related tasks. Certain advanced actions may redirect you to Fidelity’s website or require additional verification.
Is NetBenefits - Fidelity at Work safe to use for financial information?
The application is intended to provide secure access to Fidelity workplace accounts and may include safeguards such as encrypted connections, authentication controls, and device security features. However, users should still download it only from an official app store, keep the operating system updated, avoid public Wi-Fi for sensitive actions, and never disclose passwords, verification codes, or Social Security information through unsolicited messages or calls.

NetBenefits - Fidelity at Work
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via workplace.email@fidelity.com, visit http://www.netbenefits.com/, or review their https://nb.fidelity.com/public/nb/default/resourceslibrary/articles/privacypolicy.










